
High Yield Happenings: Exploiting seasonality in the bond market

Key takeaways
- September has historically been a weak month for high yield
- Equally, yields are attractive and economic fundamentals are supportive
- Artemis' high-yield strategies are positioned to exploit any seasonal weakness
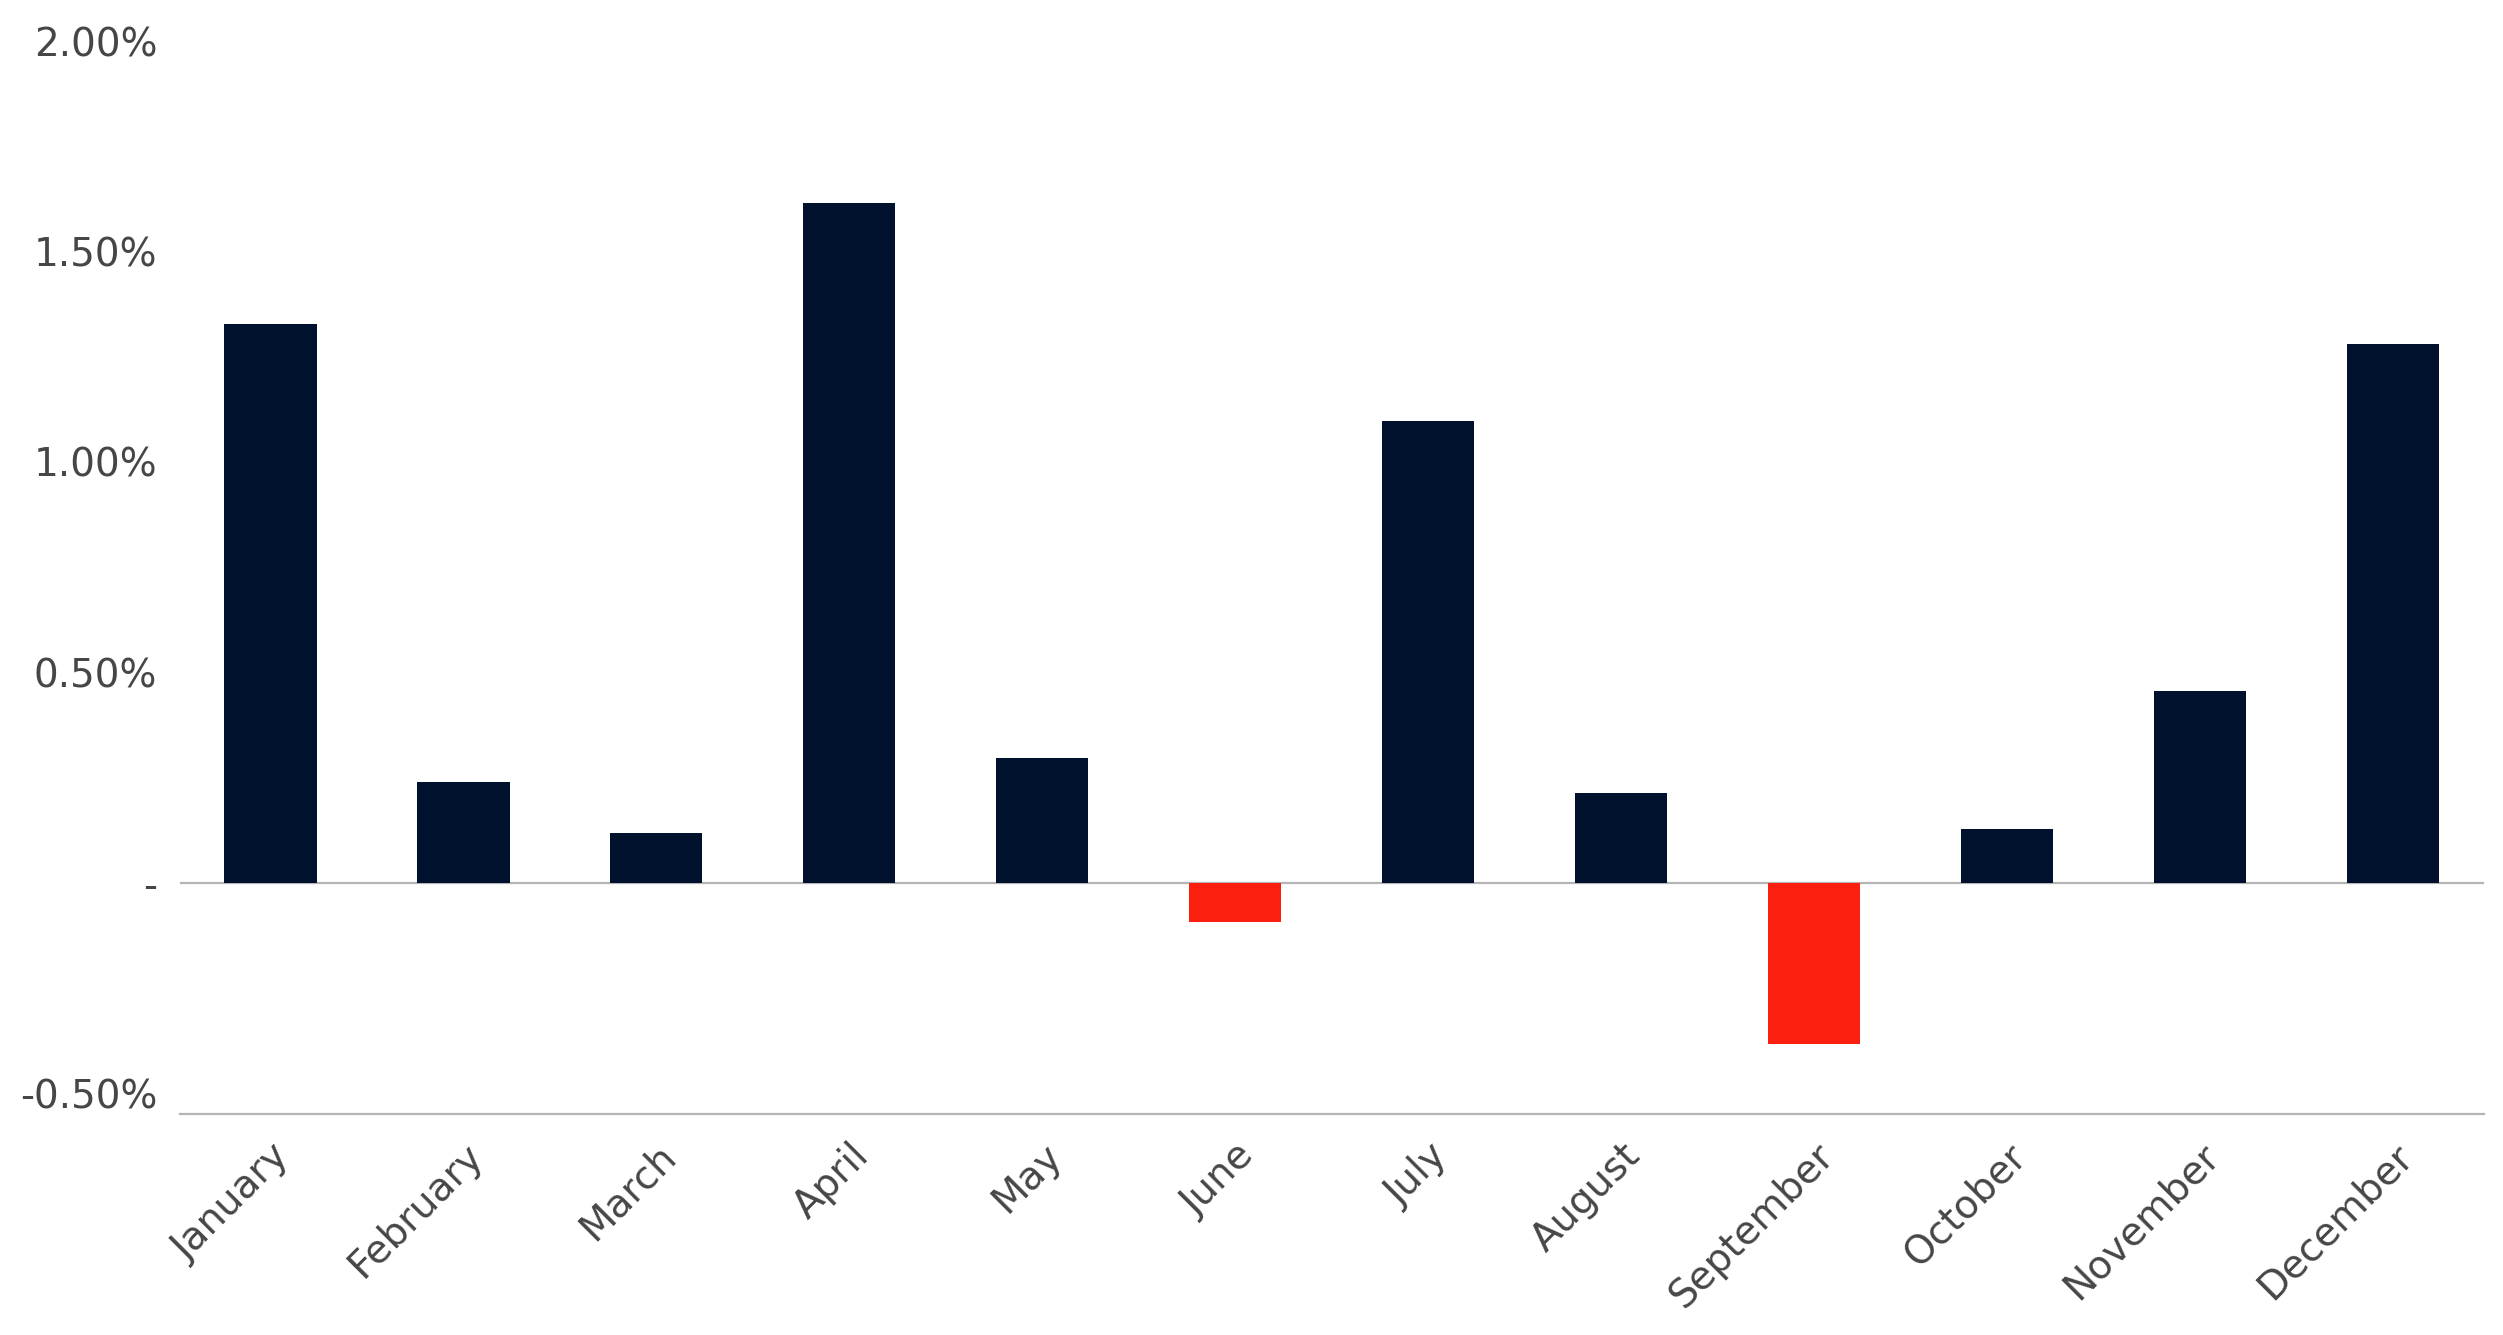
Historically, September has been a difficult month for high yield. In fact, it has been the weakest month of the year on data reaching back to 1998.1 Interestingly, that weakness has been particularly pronounced in years like this, when the US has held midterm elections. Meanwhile, credit spreads are tight (although, as we recently argued they are a long way from being too tight).
ICE BofA Global High Yield Total Return: Average Return by Calendar Month 1998-2024
September has been the weakest calendar month for high yield
Source: FactSet. Data from January 1998 to December 2024.
On the other hand, we like the companies whose bonds we own and we like the yields they offer. The broader backdrop, meanwhile, looks healthy. The second-quarter earnings season has been robust. The proportion of companies in the S&P 500 reporting positive surprises on earnings is at its highest since 20212. The manufacturing and services ISM indices are both firmly in expansionary territory3.
So what to do?
Our answer is to exploit the seasonality, not to hide from it
In Artemis Funds (Lux) – Short-Dated Global High Yield Bond, cash keeps being returned to us through coupons, calls and as bonds mature. Through September, we can simply slow the pace at which we reinvest that cash – or redirect it into a handful of favoured, lower-beta bonds. And, of course, cash will continue to arrive. We can then deploy it if prices weaken.
In Artemis Funds (Lux) – Global High Yield Opportunities, a recent change to the mandate allowing us to vary its net market exposure gives us another way to anticipate seasonality. We don’t want to sell our high-conviction credit holdings – and forgo their income – simply because September has historically been weak. Instead, we can subtract some of the fund's the broad exposure to the high-yield market by buying protection (on the iTraxx Europe Crossover, a liquid hedge on European high-yield bonds and through a small, tech-specific credit hedge). Although we pay a modest amount for that protection, we retain the income our bonds pay. We think that is more attractive than simply selling bonds.
This is tactical positioning. It is not a forecast that September will necessarily be weak. Nor is it a bearish call on high yield. The protection we have taken out is subject to change and, as things stand, we don't envision keeping it beyond the end of September.
We still like high-yield bonds. Equally, we are making sure that, if seasonal weakness does present us with a better entry price, we are ready to take advantage.
Notes and references
1. FactSet, ICE BofA Global High Yield Total Return, 1998-2024. Average return in September -0.38% vs -0.40% in midterm election years.
2. Financial Times, 2 August 2026, America’s biggest companies report ‘rock solid’ profits as consumers face higher costs
3. Institute for Supply Management - Services PMI at 54.1% July 2026 ISM Services PMI Report and Manufacturing PMI at 54.6% August 2026 ISM Manufacturing PMI Report
FOR PROFESSIONAL INVESTORS AND/OR QUALIFIED INVESTORS AND/OR FINANCIAL INTERMEDIARIES ONLY. NOT FOR USE WITH OR BY PRIVATE INVESTORS.
CAPITAL AT RISK. All financial investments involve taking risk and the value of your investment may go down as well as up. This means your investment is not guaranteed and you may not get back as much as you put in. Any income from the investment is also likely to vary and cannot be guaranteed.
This is a marketing communication. Before making any final investment decisions, and to understand the investment risks involved, refer to the fund prospectus (or in the case of investment trusts, Investor Disclosure Document and Articles of Association), available in English, and KIID/KID, available in English and in your local language depending on local country registration, available in the literature library.
Risks specific to Artemis Funds (Lux) – Short-Dated Global High Yield Bond
- Market volatility risk The value of the fund and any income from it can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
- Currency hedging risk The fund hedges with the aim of protecting against unwanted changes in foreign exchange rates. The fund is still subject to market risks, may not be completely protected from all currency fluctuations and may not be fully hedged at all times. The transaction costs of hedging may also negatively impact the fund’s returns.
- Bond liquidity risk The fund holds bonds which could prove difficult to sell. As a result, the fund may have to lower the selling price, sell other investments or forego more appealing investment opportunities.
- Higher-yielding bonds risk The fund may invest in higher-yielding bonds, which may increase the risk to capital. Investing in these types of assets (which are also known as sub-investment grade bonds) can produce a higher yield but also brings an increased risk of default, which would affect the capital value of the fund.
- Credit risk Investments in bonds are affected by interest rates, inflation and credit ratings. It is possible that bond issuers will not pay interest or return the capital. All of these events can reduce the value of bonds held by the fund.
- Derivatives risk The fund may invest in derivatives with the aim of profiting from falling (‘shorting’) as well as rising prices. Should the asset’s value vary in an unexpected way, the fund value could reduce.
- Charges from capital risk Where charges are taken wholly or partly out of a fund's capital, distributable income may be increased at the expense of capital, which may constrain or erode capital growth.
- Emerging markets risk Compared to more established economies, investments in emerging markets may be subject to greater volatility due to differences in generally accepted accounting principles, less governed standards or from economic or political instability. Under certain market conditions assets may be difficult to sell.
- Income risk The payment of income and its level is not guaranteed.
- ESG risk The fund may select, sell or exclude investments based on ESG criteria; this may lead to the fund underperforming the broader market or other funds that do not apply ESG criteria. If sold based on ESG criteria rather than solely on financial considerations, the price obtained might be lower than that which could have been obtained had the sale not been required.
Risks specific to Artemis Funds (Lux) – Global High Yield Opportunities
- Market volatility risk The value of the fund and any income from it can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
- Currency hedging risk The fund hedges with the aim of protecting against unwanted changes in foreign exchange rates. The fund is still subject to market risks, may not be completely protected from all currency fluctuations and may not be fully hedged at all times. The transaction costs of hedging may also negatively impact the fund’s returns.
- Bond liquidity risk The fund holds bonds which could prove difficult to sell. As a result, the fund may have to lower the selling price, sell other investments or forego more appealing investment opportunities.
- Higher-yielding bonds risk The fund may invest in higher-yielding bonds, which may increase the risk to capital. Investing in these types of assets (which are also known as sub-investment grade bonds) can produce a higher yield but also brings an increased risk of default, which would affect the capital value of the fund.
- Credit risk Investments in bonds are affected by interest rates, inflation and credit ratings. It is possible that bond issuers will not pay interest or return the capital. All of these events can reduce the value of bonds held by the fund.
- Derivatives risk The fund may invest in derivatives with the aim of profiting from falling (‘shorting’) as well as rising prices. Should the asset’s value vary in an unexpected way, the fund value could reduce.
- Leverage risk The fund may operate with a significant amount of leverage. Leverage occurs when the economic exposure created by the use of derivatives is greater than the amount invested. A leveraged portfolio may result in large fluctuations in its value and therefore entails a high degree of risk including the risk that losses may be substantial.
- Charges from capital risk Where charges are taken wholly or partly out of a fund's capital, distributable income may be increased at the expense of capital, which may constrain or erode capital growth.
- Emerging markets risk Compared to more established economies, investments in emerging markets may be subject to greater volatility due to differences in generally accepted accounting principles, less governed standards or from economic or political instability. Under certain market conditions assets may be difficult to sell.
- Income risk The payment of income and its level is not guaranteed.
- Counterparty risk Investments such as derivatives are made using financial contracts with third parties. Those third parties may fail to meet their obligations to the fund due to events beyond the fund's control. The fund's value could fall because of loss of monies owed by the counterparty and/or the cost of replacement financial contracts.
- ESG risk The fund may select, sell or exclude investments based on ESG criteria; this may lead to the fund underperforming the broader market or other funds that do not apply ESG criteria. If sold based on ESG criteria rather than solely on financial considerations, the price obtained might be lower than that which could have been obtained had the sale not been required.
Important information
The intention of Artemis’ ‘investment insights’ articles is to present objective news, information, data and guidance on finance topics drawn from a diverse collection of sources. Content is not intended to provide tax, legal, insurance or investment advice and should not be construed as an offer to sell, a solicitation of an offer to buy, or a recommendation for any security or investment by Artemis or any third-party. Potential investors should consider the need for independent financial advice. Any research or analysis has been procured by Artemis for its own use and may be acted on in that connection. The contents of articles are based on sources of information believed to be reliable; however, save to the extent required by applicable law or regulations, no guarantee, warranty or representation is given as to its accuracy or completeness. Any forward-looking statements are based on Artemis’ current opinions, expectations and projections. Articles are provided to you only incidentally, and any opinions expressed are subject to change without notice. The source for all data is Artemis, unless stated otherwise. The value of an investment, and any income from it, can fall as well as rise as a result of market and currency fluctuations and you may not get back the amount originally invested.
