Artemis Funds (Lux) – US Smaller Companies
Q2 2026 update

Source for all information: Artemis as at 30 June 2026, unless otherwise stated.
On 12 January 2026, the market capitalisation restriction limits for Artemis Funds (Lux) – US Smaller Companies and the Artemis US Smaller Companies Fund were amended. The funds now commit to principally invest in shares of smaller companies which, when first acquired, have a market value of less than $20bn, previously $10bn.
Review of the quarter to 30 June 2026
• The fund outperformed, returning 25.3% compared with 21.4% for its benchmark
• Contributors included Seagate, Coherent, Applied Optoelectronics, Bloom Energy and MKS
• Detractors included Primoris Services, Hasbro, Globus Medical and CenterPoint Energy
• Markets are now looking beyond the Middle East conflict and focusing on company fundamentals
The second quarter marked a significant shift in market sentiment. While April was dominated by concerns over war in the Middle East and the expectation of persistently higher energy prices, these fears eased considerably by quarter end following the announcement of an interim agreement between the US and Iran. Brent crude recorded its largest quarterly decline since the pandemic, helping to alleviate inflation concerns and allowing investors to focus on the resilience of the US economy and corporate earnings.
Against this backdrop, US smaller companies performed well as confidence in the domestic economy improved. Employment data remained resilient throughout the quarter and earnings expectations strengthened across a broader range of companies, supporting performance beyond the largest technology stocks.
The Russell 2000 continues to outperform the S&P 500. Within the small-cap index, technology remained a strong performer amid ongoing investment in AI infrastructure, while industrial companies also benefited from improving economic sentiment.
Although the Federal Reserve adopted a more hawkish tone as economic data remained firm, the easing of inflation pressures following the decline in oil prices helped support risk assets into quarter end.
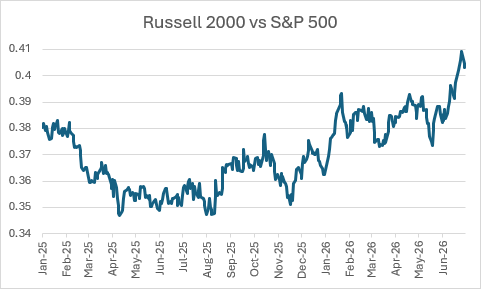
Source: Bloomberg as at 30 June 2026
Performance
We were pleased that the fund outperformed convincingly in a rallying market. It returned 25.3% during the quarter, compared with 21.4% for its Russell 2000 NTR (Standard) benchmark (in US dollars).
| Three months | Six months | One year | Three years | Five years | |
|---|---|---|---|---|---|
| Artemis (Lux) Smaller Companies Fund | 25.3% | 24.8% | 46.4% | 94.1% | 49.8% |
| Russell 2000 TR / Russell 2000 NTR (Standard)* | 21.4% | 22.4% | 40.3% | 65.7% | 39.2% |
| US Small-Cap Equity average | 21.9% | 20.4% | 32.8% | 56.5% | 34.4% |
Past performance is not a guide to the future. Source: Lipper Limited/Artemis as at 3 June 2026 for class I Acc USD. All figures show total returns with dividends and/or income reinvested, net of all charges. Performance does not take account of any costs incurred when investors buy or sell the fund. Returns may vary as a result of currency fluctuations if the investor's currency is different to that of the class.
*As at 6 Aug 2024 the benchmark changed to Russell 2000 NTR (Standard). Returns up to 6 Aug 2024 reflect those of the Russell 2000 TR.
Fund 10-year discrete performance
| 2025 | 2024 | 2023 | 2022 | 2021 | 2020 | 2019 | 2018 | 2017 | 2016 | |
| Artemis Funds (Lux) – US Smaller Companies | 13.0% | 23.2% | 18.9% | -28.7% | 17.3% | 28.6% | 30.7% | n/a | n/a | n/a |
| Russell 2000 TR / Russell 2000 NTR (Standard)* | 12.4% | 11.4% | 16.9% | -20.4% | 14.8% | 20.0% | 25.5% | n/a | n/a | n/a |
Past performance is not a guide to the future. Source: Lipper Limited/Artemis as at 31 December 2025 for class I Acc USD.
*As at 6 Aug 24 the benchmark changed to Russell 2000 NTR (Standard). Returns up to 6 Aug 24 reflect those of the Russell 2000 TR.
Positives
Seagate (data storage) and Coherent (networking for data centres) continue to make a positive contribution to performance, thanks to robust AI-driven data centre demand and a tight market for storage and networking.
Fibre-optic networking company Applied Optoelectronics performed well after announcing it would ramp up capacity to supply lasers to hyperscale data centres. We have since sold our position, taking profits.
MKS, a supplier of equipment for semiconductor manufacturing, was another beneficiary of AI infrastructure demand.
Bloom Energy continues to perform well. We believe it will gain further market share in power generation as it delivers fuel cells to data centres at significantly faster speeds than legacy providers of energy equipment. One particular highlight was the news its infrastructure partnership with Brookfield Asset Management had been upsized by fivefold to $25bn. We are looking forward to hearing more from the company when it reports earnings.
Negatives
Texas-based utility CenterPoint Energy saw mixed performance. As a regulated utility with above-average growth visibility, the company held up better than its sector, despite underperforming the broader market. The company entered a new equity distribution agreement for up to $1bn of common stock, which weighed on the share price.
Globus Medical, which develops products for spine procedures, demonstrated robust execution of its strategy with strong profit margins. However, it suffered from the wider sell-off in medtech.
Primoris Services, which provides skilled labour for power utility end markets, reported earnings that were well below expectations. We sold out of the position, since when it has continued to underperform.
Like other consumer names, toy and game business Hasbro suffered from the fallout of higher oil prices during Q2. We expect this cloud to lift as tensions ease in the Middle East and US consumers receive tax refunds.
Activity
We trimmed Coherent (networking for data centres) and sold out of Applied Optoelectronics (fibre optic networking) after strong performance, taking profits and recycling capital into new positions.
These include cloud communications platform Twilio, which we think will be an AI winner and has delivered positive EPS growth. We also started a position in Onto Innovation, which provides services to the semiconductor industry, such as process control, metrology and software analytics.
As outlined above, we sold out of Primoris Services on the back of disappointing results.
Axon Enterprise has been caught up in the underperformance of software this year on fears of AI disruption. We do not agree with this view: Axon occupies a unique position as a technology partner providing hardware and software to police departments and has developed a significant AI platform over the past couple of years. After reducing our exposure in the previous quarter, we have started to rebuild our position.
In terms of positioning, the fund is overweight industrials, utilities and technology. Since the first quarter of this year, we have increased our weighting to basic materials while reducing our consumer staples exposure.
Outlook
The market's focus appears to have shifted away from geopolitical concerns and back towards the strength of the underlying US economy and the path of interest rates. While higher bond yields may continue to create periods of volatility, the fragile ceasefire in the Middle East has seen these retreat and oil prices move lower. In addition, recent economic data has remained resilient, corporate earnings expectations continue to improve and there has been a broadening of upwards earnings revisions. We hope to see this trend continuing in the upcoming results season.
It is also worth noting that manufacturing data remained expansionary through June, following nearly three years of contracting. We believe this provides a supportive backdrop for fundamentally strong small- and mid-cap companies able to deliver differentiated growth.
The buildout of AI infrastructure is another important theme. The hyperscalers’ investment plans, prospective public listings of companies such as Anthropic and OpenAI (and the recent IPO of SpaceX) and equity raises by the likes of Alphabet reinforce our conviction that investment in AI infrastructure has further to run. We continue to see attractive opportunities in businesses supplying the hardware, software and services underpinning this buildout.
While AI is an important area of opportunity, our investment approach continues to be driven by bottom-up stock selection. We remain focused on identifying high-quality companies with differentiated, long-term growth prospects, where company-specific fundamentals (rather than macroeconomic outcomes) are the primary drivers of value creation.
CAPITAL AT RISK. All financial investments involve taking risk and the value of your investment may go down as well as up. This means your investment is not guaranteed and you may not get back as much as you put in. Any income from the investment is also likely to vary and cannot be guaranteed.
This is a marketing communication. Before making any final investment decisions, and to understand the investment risks involved, refer to the fund prospectus (or in the case of investment trusts, Investor Disclosure Document and Articles of Association), available in English, and KIID/KID, available in English and in your local language depending on local country registration, available in the literature library.
Risks specific to Artemis Funds (Lux) – US Smaller Companies
- Market volatility risk The value of the fund and any income from it can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
- Currency risk The fund’s assets may be priced in currencies other than the fund base currency. Changes in currency exchange rates can therefore affect the fund's value.
- Charges from capital risk Where charges are taken wholly or partly out of a fund's capital, distributable income may be increased at the expense of capital, which may constrain or erode capital growth.
- Smaller companies risk Investing in small companies can involve more risk than investing in larger, more established companies. Shares in smaller companies may not be as easy to sell, which can cause difficulty in valuing those shares.
- ESG risk The fund may select, sell or exclude investments based on ESG criteria; this may lead to the fund underperforming the broader market or other funds that do not apply ESG criteria. If sold based on ESG criteria rather than solely on financial considerations, the price obtained might be lower than that which could have been obtained had the sale not been required.
The intention of Artemis’ ‘investment insights’ articles is to present objective news, information, data and guidance on finance topics drawn from a diverse collection of sources. Content is not intended to provide tax, legal, insurance or investment advice and should not be construed as an offer to sell, a solicitation of an offer to buy, or a recommendation for any security or investment by Artemis or any third-party. Potential investors should consider the need for independent financial advice. Any research or analysis has been procured by Artemis for its own use and may be acted on in that connection. The contents of articles are based on sources of information believed to be reliable; however, save to the extent required by applicable law or regulations, no guarantee, warranty or representation is given as to its accuracy or completeness. Any forward-looking statements are based on Artemis’ current opinions, expectations and projections. Articles are provided to you only incidentally, and any opinions expressed are subject to change without notice. The source for all data is Artemis, unless stated otherwise. The value of an investment, and any income from it, can fall as well as rise as a result of market and currency fluctuations and you may not get back the amount originally invested.