Regime change: from roadmap to reality

Key takeaways
- The impact of ‘regime change’ on the share prices of longstanding holdings such as Rheinmetall has been dramatic.
- As the process of regime change evolves, we have moved on from some of the companies we were investing in five years ago.
- Our focus now is on those companies where the effects of regime change have yet to be fully priced in.
Which of these companies' shares would you rather own? A lossmaking 'interactive fitness platform', selling static bicycles and subscriptions to online exercise and wellness classes? Or mainland Europe's biggest defence contractor, a business with an €80.5 billion order backlog that envisages its sales quintupling by 20301?
Today, the answer might appear self-evident. Five years ago – judging by some investors' portfolios – it was less clear-cut. Capital-light platform businesses like Peloton were in, capital-intensive industrial stocks like Rheinmetall were out. Near-zero interest rates and QE had forced the discount rate lower, inflating the multiples on which lossmaking growth stocks traded. Peloton's share price rose by 434% in 2020. Rheinmetall's fell by 11%2. Back then, we were in a world where people were sitting at home fighting Covid. Today we are in a world where countries are fighting each other.
Charting five years of regime change: Peloton vs Rheinmetall
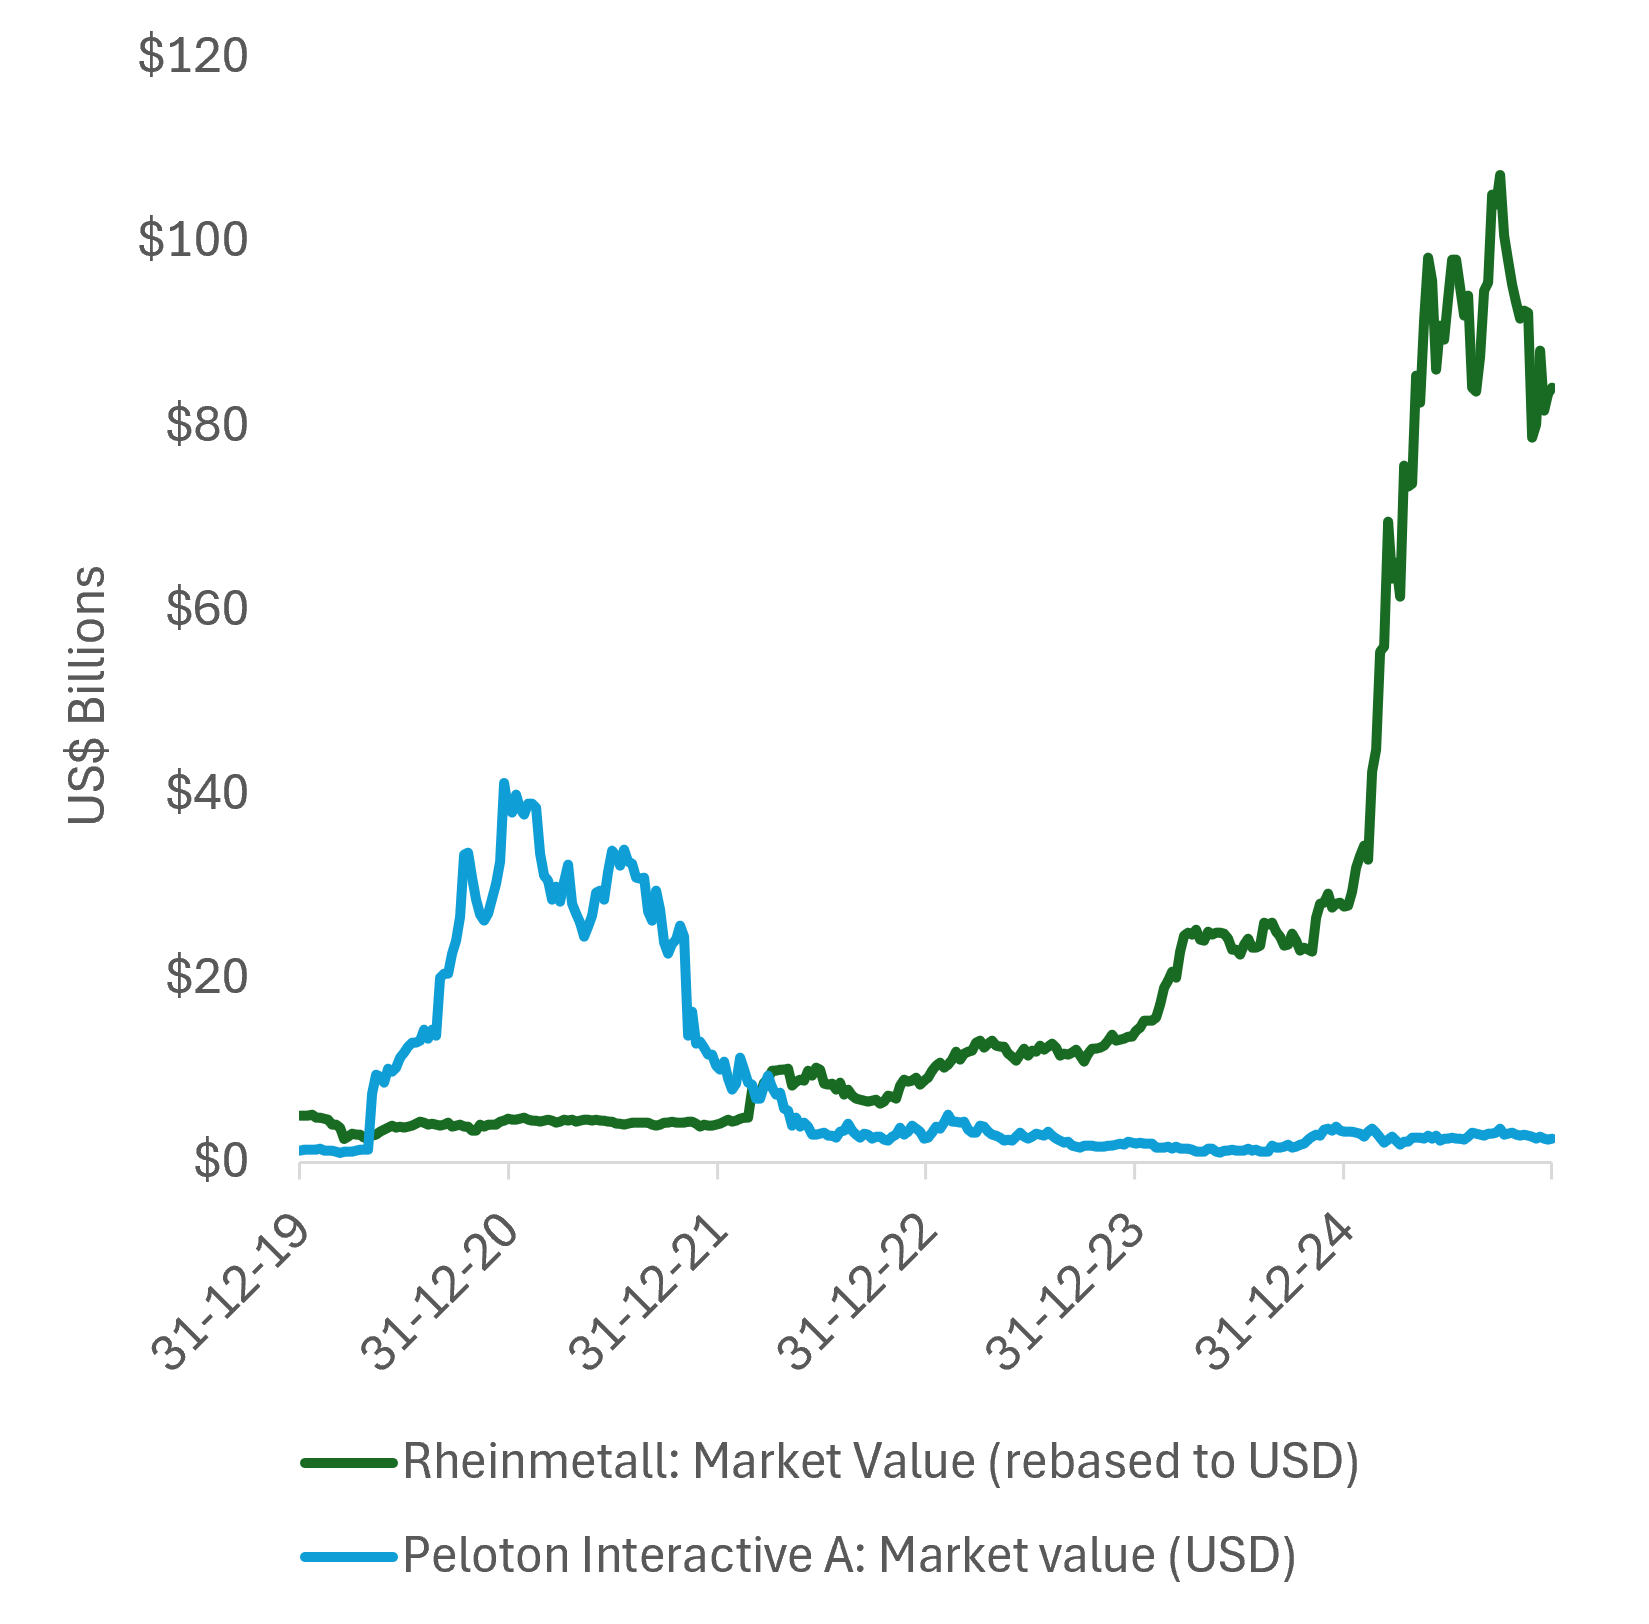
Source: FactSet, Artemis as at 31 December 2025
Our Global Value strategy3 did not hold Peloton in 2021. Instead, alongside Rheinmetall, its investments included names you'll find in it today: miners (such as Glencore); semiconductor manufacturers (such as Samsung Electronics); and defence contractors (such as Korea’s Hanwha Aerospace). This wasn't solely due to these stocks' valuations, dividends or even their free cashflow yields. It was because they were all companies where we could identify catalysts for their shares to be re-rated.
We refer to a roadmap to find stocks where there are catalysts for rerating
We are not thematic investors; we are pragmatists. Equally, we try to understand the world that companies operate in. To do that, we refer to a top-down roadmap. And as the post-pandemic world began to emerge, we updated that roadmap to describe several powerful, secular trends that we believed would shape returns from financial markets for years or even decades to come. Collectively, we described those processes and secular transitions as a 'regime change' and we consciously invested our clients' capital in companies that were aligned with it. 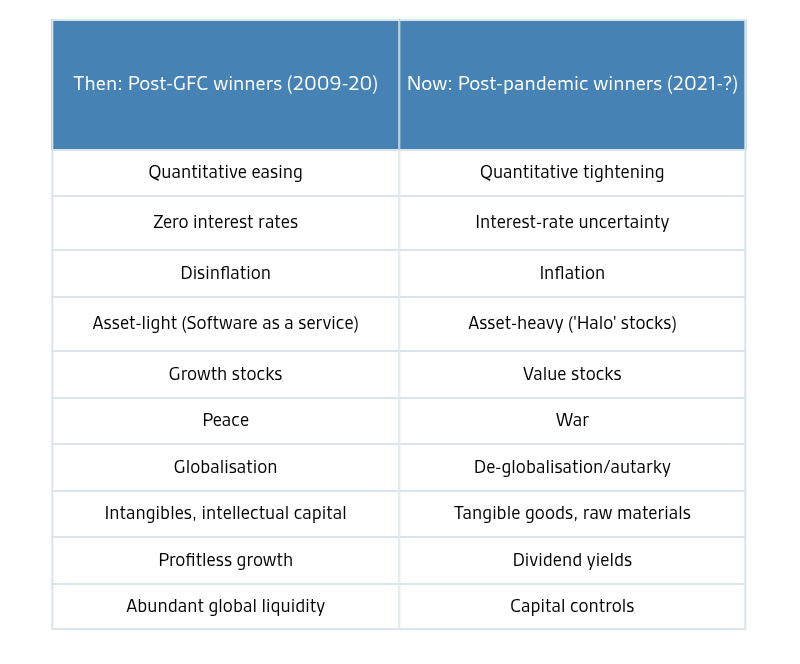
Two aspects of ‘regime change’ and its early beneficiaries
1. Higher interest rates and steeper yield curves (banks)
One important component of our regime change thesis was that the world was moving from a disinflationary regime into an era in which inflation would be higher and more volatile than it was in the decade following the financial crisis. Gone were the days of inflation undershooting central banks’ targets. In the short term, the fiscal stimulus governments applied during the Covid lockdowns and the fracturing of supply chains supplied a powerful inflationary impulse. Beneath that, however, we identified longer-lasting trends: the rise of economic nationalism and the reversal of globalisation, tariffs, onshoring, and a waning of the deflationary impulse that China's entry into the global trade system once provided.
We saw banks, particularly in Europe, as the clearest beneficiaries of a new era of higher inflation, higher interest rates and steeper yield curves. After the financial crisis, banks de-leveraged, de-risked and were constrained from engaging in speculative activities or over-extending their credit books. As a result, they began to focus on more traditional deposit-taking and lending and to resemble highly cash-generative utilities. As interest rates rose from 2022 onwards, banks found they could charge higher rates to lend, while the interest they paid on deposits increased more slowly. The profits they generated for their shareholders returned to levels not seen for many years. As a result, the Artemis Global Value strategy4 has enjoyed particularly strong returns from its holdings in European banks such as Germany's Commerzbank and Italy's Banco BPM over the past five years5.
2. Geopolitical tensions and war (defence stocks)
The stockpiling of vaccines during the pandemic hinted at the transition to a more nationalistic world. The following five years saw a steady erosion of the post-war international consensus and its replacement by a new emphasis on national resilience and security. Russia's invasion of Ukraine, meanwhile, may have marked the end of ‘Pax Americana’ and the termination of the peace dividend Europe had been harvesting since the end of the Cold War.
Guided by our roadmap, we were investing in defence companies before governments across Europe decided to re-arm. The re-ratings that followed were dramatic:
- Rheinmetall's p/e rose from 14x in January 2020 to 36x by April 2026.
- Mitsubishi Heavy Industries’ p/e climbed from 10x in February 2022 to 45x by February 20266.
‘Regime change’ isn’t over – but it is evolving
We do not expect a return to the pre-pandemic regime of low inflation, expanding global trade and falling rates. Although we took profits on Rheinmetall in the first half of 2026, we still invest in defence stocks and banks. But parts of the new regime have now become the new normal. Our task is to identify where the extent and duration of change continues to be underestimated or where its second-order effects are yet to be reflected in share prices. A number of these opportunities are aligned to one of the following three themes.
Our task is to identify where the extent and duration of change continues to be underestimated or where its second-order effects are yet to be reflected in share prices.
1. Capital investment across the energy sector
One foundational element of our regime-change thesis was that a long period of underinvestment in the physical economy (particularly across the energy, resource, utility and infrastructure sectors) would oblige the world to commit billions of dollars of capital to maintain supplies. With Western energy companies being run to deliver cash to their shareholders or to signal their alignment with the energy transition, capital was diverted away from physical investments and towards environmental improvements or share buybacks7. This often came at the expense of developing new energy fields and renewing transmission networks and refineries. As a consequence, proven energy reserves have been depleted, and rusting infrastructure needs to be replaced.
That need for investment is underscored by concerns around global energy security. The vulnerabilities that result from depending on energy produced in unstable regions or by hostile actors became clear when Russia launched its full-scale invasion of Ukraine. And as the attack on the Ras Laffan energy complex in Qatar earlier this year made clear, it might be unwise to depend too heavily on the Middle East8. Instead, energy importers might need to turn to friendly nations such as the US or Norway. That, in turn, points to the need for more investment.
Stocks aligned to this area of our roadmap: Tenaris, Baker Hughes, AkerBP, Var Energy, Diversified Energy.
2. Supplying the technology investment boom
Long before the AI infrastructure boom pushed the hyperscalers’ expected capital spending towards $800 billion this year alone9, we had positioned our portfolio in anticipation of a wave of reindustrialisation. Geopolitical tensions – particularly between the US and China – were creating pressure to onshore certain types of production. Self-sufficiency, control and reliability of supply were already starting to take precedence over cost.
In 2022, the Biden administration's Chips Act gave companies financial incentives to assemble semiconductors at plants in the US10. The pressure to onshore production has intensified through the second Trump administration. Apple will invest $600 billion in moving parts of its supply chain and advanced manufacturing to the US through its 'American Manufacturing Program'11. This wave of capex has been intensified by the AI datacentre boom. We don't tend to focus on the companies making these multi-billion investments. Instead, we invest in their suppliers – companies that make the gas turbines needed to power data centres, the semiconductors and memory chips needed to run AI systems and the cabling to wire them up.
Stocks aligned to this area of our roadmap: Prysmian, Samsung Electronics, Dongfang Electric, Harbin Electric, Nexans.
3. Raw materials and emerging markets
Building physical infrastructure such as semiconductor fabs and data centres requires vast quantities of raw materials, particularly industrial metals. BHP estimates that copper use in data centres globally will grow sixfold by 2050 – from around half a million tonnes a year today to around three million tonnes a year by 205012. That is equivalent to the combined annual output of the world's four largest copper mines.
This hunger for raw materials points us towards mining companies and, by extension, emerging markets. If demand from the AI hyperscalers is to be met, capital will need to be directed towards digging new mines and building smelters in areas of the world where raw materials are produced, such as Brazil and South Africa. The resulting flows of capital could, in time, promote a rebalancing of the world economy and add to the downward pressures on the dollar while underwriting emerging-market currencies. That, in turn, should benefit emerging-market banks, financial stocks and consumers.
Stocks aligned to this area of our roadmap: Freeport-McMoRan, Glencore, Grupo Mexico, Ternium.
As regime change evolves, so does our portfolio
Although many of the underlying trends we identified five years ago remain in place, that knowledge has less value if it is already reflected in share prices. So, as regime change evolves, we have moved on from some of the names we held five years ago.
As we look into 2027 and into the next decade, we cannot simply position the portfolio in anticipation of the transition to a new regime and wait for our stocks to be re-rated as markets catch up with reality. No trend moves in a perfectly straight line and there will be periods in which, for example, energy stocks, miners and semiconductor stocks underperform. As active investors, we must be ready to react to that and, where we can, anticipate it.
So our task is to exploit the opportunities that volatility creates without losing sight of the overall direction of travel. The ongoing, deeper secular processes of change highlighted by our roadmap persist. It takes 10 years to develop an offshore oil field; it can take an average of 18 years to develop a new mine13. While roadmaps need to be updated regularly, they remain indispensable to careful drivers.
Artemis Funds (Lux) Global Value: Objective
The fund's objective is to increase the value of shareholders’ investments primarily through capital growth over a five-year period. The fund is actively managed.
Notes and references
1. Rheinmetall, 6 August 2026, H1: Strong sales growth and record profitability
2. Artemis, FactSet as at 30 June 2026
3 & 4. The Global Value strategy referred to here is a UK-domiciled fund with a similar investment process run by the same investment team. It is being shown to illustrate the approach of the team and should not be seen as a promotion of the UK-domiciled strategy which is not registered for sale in the EU and Switzerland.
5. Artemis, FactSet as at 30 June 2026
6. Artemis, LSEG as at 31 May 2026
7. McKinsey & Company, April 2026, The discovery gap: What it means for oil and gas exploration
8. Reuters, 19 March 2026, Iran attacks wipe out 17% of Qatar’s LNG capacity for up to five years, QatarEnergy CEO says
9. Bloomberg, 25 September 2026, Goldman Sees Hyperscaler AI Capex Rising 50% to $1.2 Trillion
10. National Institute of Standards and Technology – CHIPS for America
11. Apple, 6 August 2025 – Apple increases U.S. commitment to $600 billion, announces American Manufacturing Program
12. BHP 20 January 2025 – Why AI tools and data centres are driving copper demand
13. S&P Global Market Intelligence, 10 April 2024, Average lead time almost 18 years for mines started in 2020–23
FOR PROFESSIONAL INVESTORS AND/OR QUALIFIED INVESTORS AND/OR FINANCIAL INTERMEDIARIES ONLY. NOT FOR USE WITH OR BY PRIVATE INVESTORS.
CAPITAL AT RISK. All financial investments involve taking risk and the value of your investment may go down as well as up. This means your investment is not guaranteed and you may not get back as much as you put in. Any income from the investment is also likely to vary and cannot be guaranteed.
This is a marketing communication. Before making any final investment decisions, and to understand the investment risks involved, refer to the fund prospectus (or in the case of investment trusts, Investor Disclosure Document and Articles of Association), available in English, and KIID/KID, available in English and in your local language depending on local country registration, available in the literature library.
Risks specific to Artemis Funds (Lux) – Global Value
- Market volatility risk The value of the fund and any income from it can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
- Currency risk The fund’s assets may be priced in currencies other than the fund base currency. Changes in currency exchange rates can therefore affect the fund's value.
- Charges from capital risk Where charges are taken wholly or partly out of a fund's capital, distributable income may be increased at the expense of capital, which may constrain or erode capital growth.
- Emerging markets risk Compared to more established economies, investments in emerging markets may be subject to greater volatility due to differences in generally accepted accounting principles, less governed standards or from economic or political instability. Under certain market conditions assets may be difficult to sell.
- China risk The fund can invest in China A-shares (shares traded on Chinese stock exchanges in Renminbi). There is a risk that the fund may suffer difficulties or delays in enforcing its rights in these shares, including title and assurance of ownership.
Important information
The intention of Artemis’ ‘investment insights’ articles is to present objective news, information, data and guidance on finance topics drawn from a diverse collection of sources. Content is not intended to provide tax, legal, insurance or investment advice and should not be construed as an offer to sell, a solicitation of an offer to buy, or a recommendation for any security or investment by Artemis or any third-party. Potential investors should consider the need for independent financial advice. Any research or analysis has been procured by Artemis for its own use and may be acted on in that connection. The contents of articles are based on sources of information believed to be reliable; however, save to the extent required by applicable law or regulations, no guarantee, warranty or representation is given as to its accuracy or completeness. Any forward-looking statements are based on Artemis’ current opinions, expectations and projections. Articles are provided to you only incidentally, and any opinions expressed are subject to change without notice. The source for all data is Artemis, unless stated otherwise. The value of an investment, and any income from it, can fall as well as rise as a result of market and currency fluctuations and you may not get back the amount originally invested.