High yield happenings: there is no 'bloodbath'


Key takeaways
- Default risk is concentrated in CCC bonds.
- The overall high-yield market is significantly higher quality than in past cycles.
- Artemis' high-yield funds are deliberately much lighter in CCCs than the wider market.
British journalists have a colourful term, 'marmalade dropper', to describe a headline so arresting that readers drop their morning toast. By the measured standards of the Financial Times, one recent headline – "Junk debt rout sparks ‘bloodbath’ for credit investors" – surely qualifies.
If the FT's intention was to prompt clicks from high-yield analysts, I can confirm it worked. But while it’s a vivid piece of imagery, the recent pressures on some CCC rated credits should not be taken as representative of the wider high-yield market.
1) The risk of default is concentrated in CCC rated bonds
Although the rise in yields has undoubtedly increased the refinancing pressures some borrowers face, we believe the risks are concentrated in a select group of CCC rated issuers.
Default risk ultimately depends on the interaction between i) refinancing costs, ii) underlying credit quality and iii) sector-specific vulnerabilities. For most BB and B rated issuers, refinancing costs remain manageable. Refinancing risk is much more concentrated in the CCC rated part of the market. Median yields there currently stand at 10.4%, versus a median existing coupon of 6.8%, implying that if these companies needed to refinance today, their borrowing costs would increase by 3.6 percentage points1.
And although refinancing costs will vary from one CCC rated issuer to the next, that gap illustrates the significant increase in marginal funding costs they now face. Refinancing at these levels could make existing capital structures increasingly difficult to sustain for those issuers with weaker free cash flows and/or high levels of debt.
2) CCCs are now only a small proportion of the high-yield market
The wider impact of the stresses emerging in CCC rated bonds should not be overstated. The quality of the high-yield market as a whole has improved materially over time. Immediately prior to the Global Financial Crisis, CCC rated credit represented around 17% of the high-yield market; BB rated bonds only accounted for around 40%. Today, CCC rated bonds account for just 6% of the market while BB rated bonds are comfortably in the majority, accounting for around 63%2.
An increase in quality - and a contraction in the CCC rated part of the market - have reduced the chance of a large default cycle
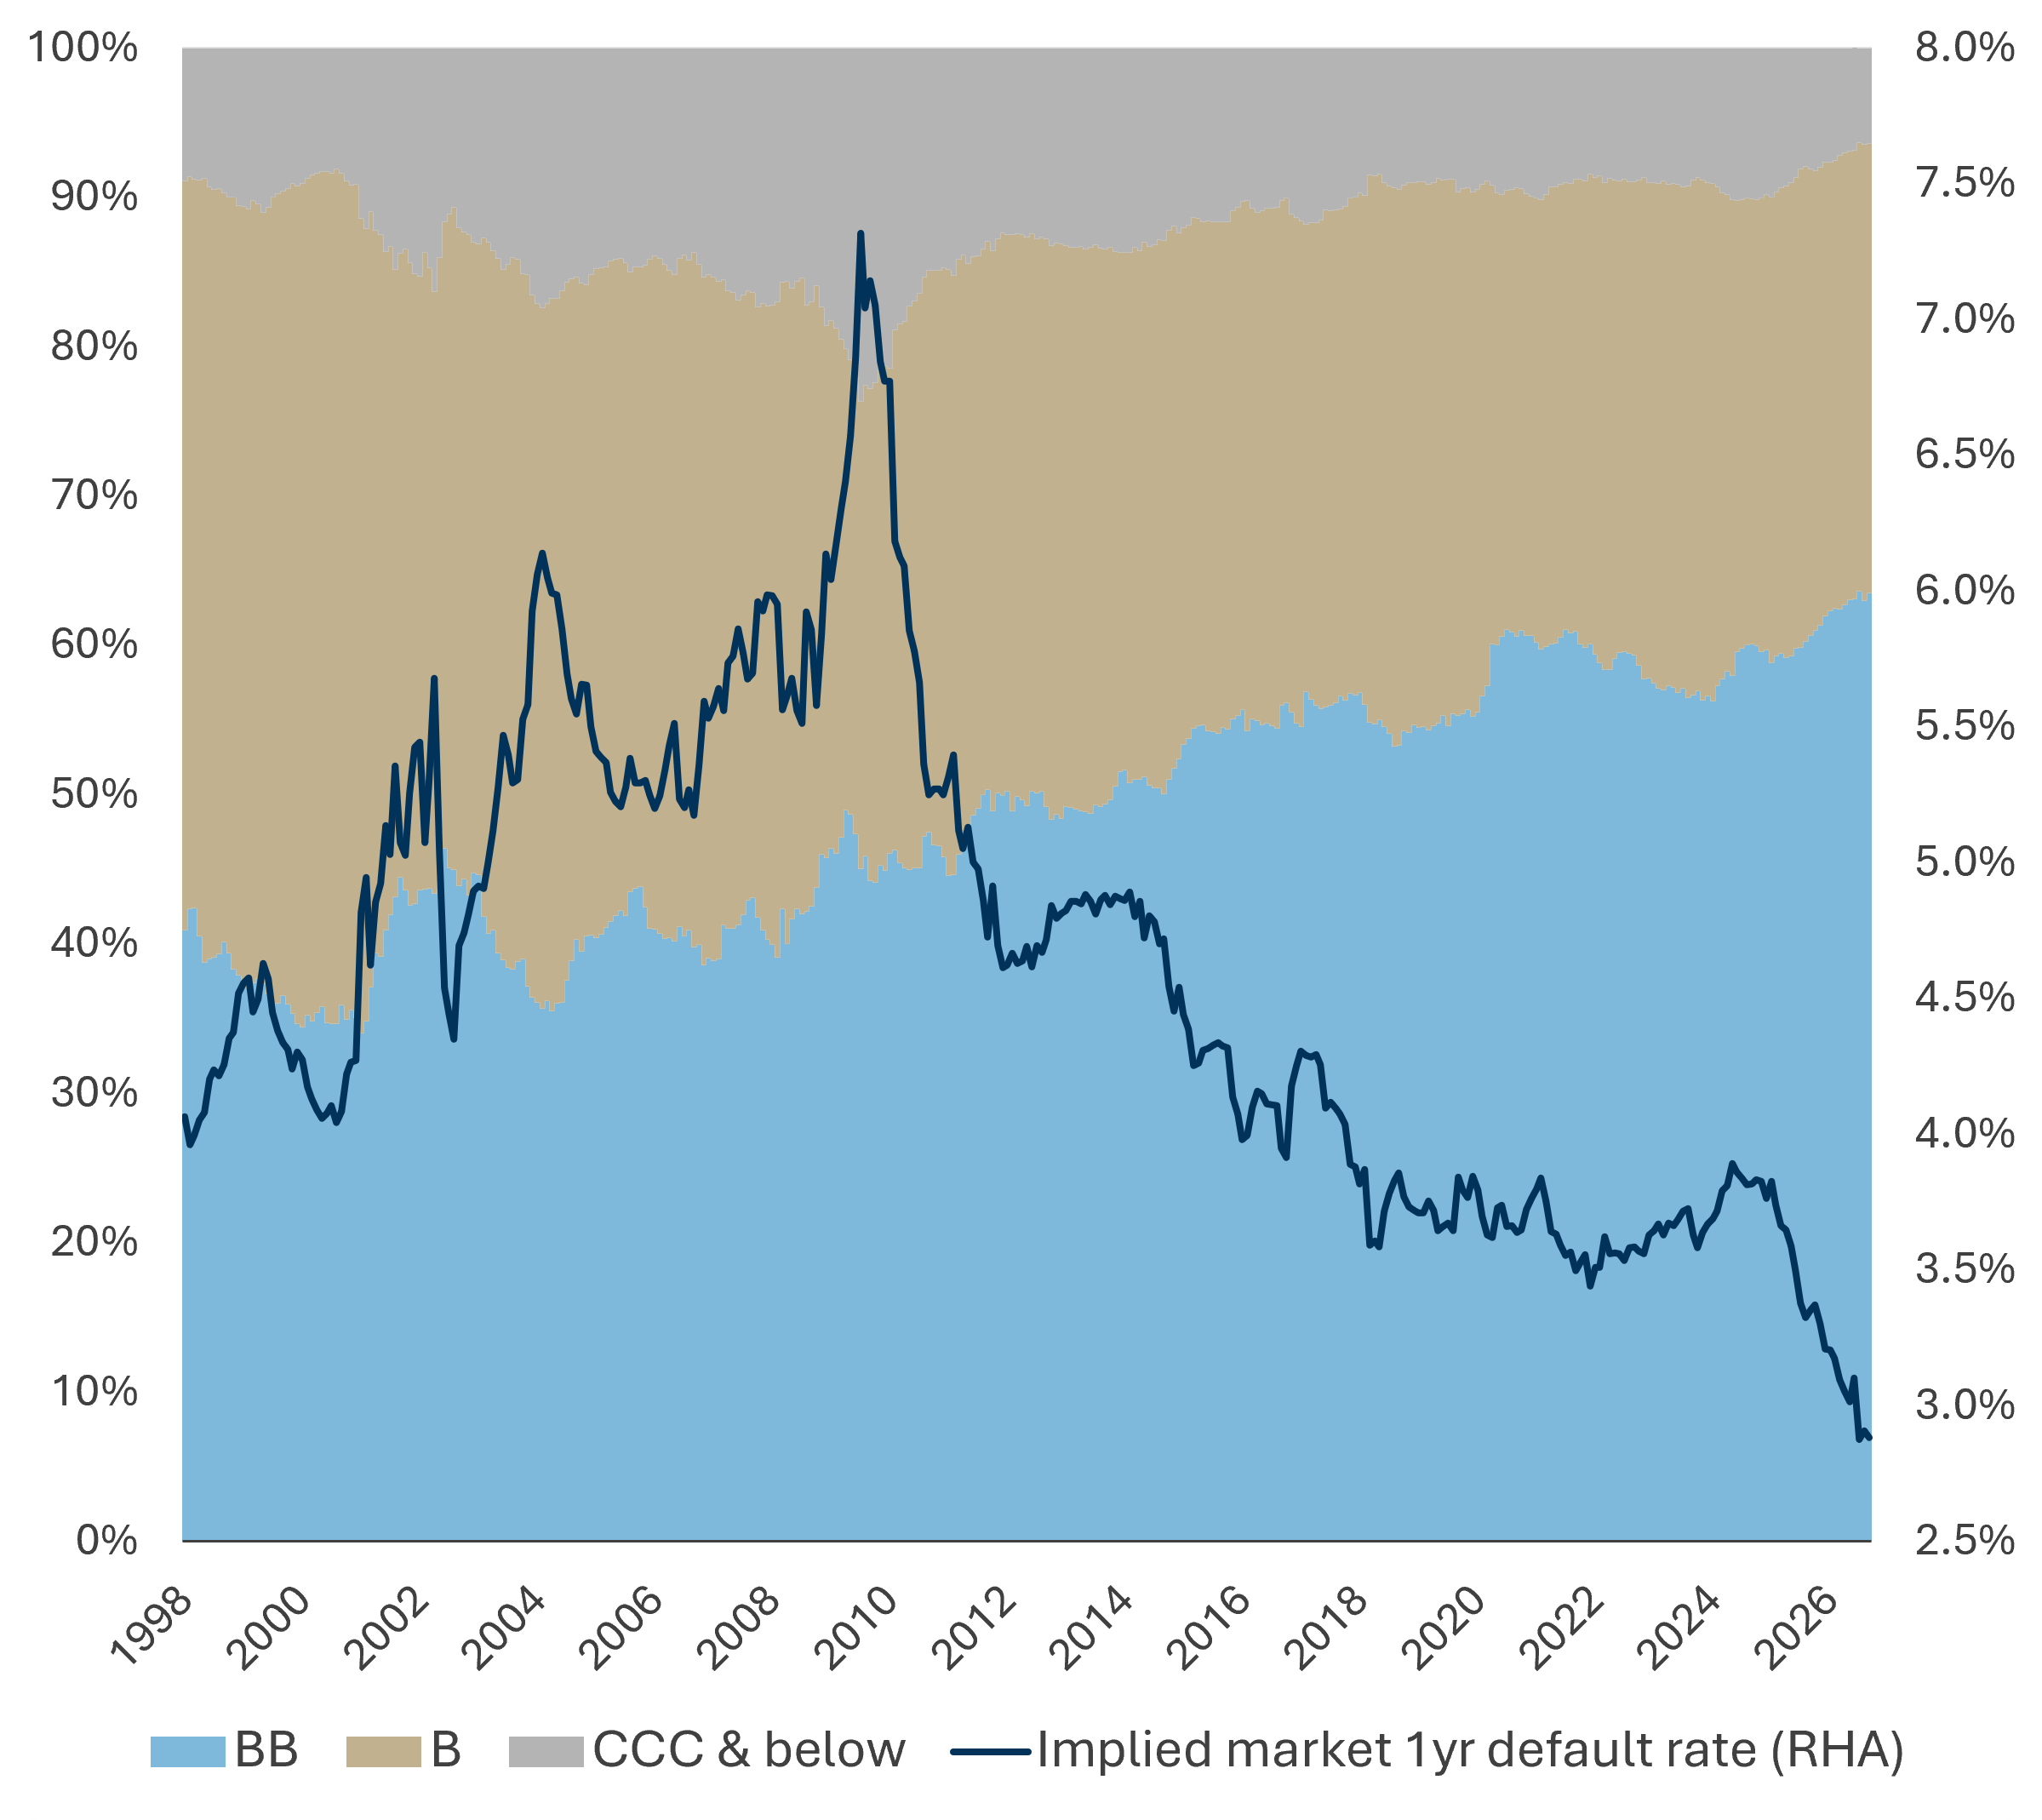
ICE BofA Merrill Lynch Global High Yield Constrained Index as at 30 September 2026. Implied market 1yr default rate is based on S&P median default rates 1981-2021.
This reflects a structural change in credit markets since the financial crisis. Tighter regulation increased the cost to banks of using their balance sheets to warehouse risk, reducing their willingness to underwrite lower-rated credit3. At the same time, the growth of private credit provided an alternative source of funding for more leveraged issuers who would previously have sought to finance themselves in the public market4.
As a result, even if the number of defaults were to increase, the significantly higher starting quality of the high-yield market, and the dramatically reduced proportion of issuers most exposed to refinancing stresses, should make a broad, systemic default cycle far less likely than in previous downturns.
3) The CCC universe has changed
The sector composition of the CCC rated part of the market is quite different today than it was in previous cycles. Historically, cyclical sectors predominated in the CCC rated area of the market so stresses tended to emerge there alongside a broader economic downturn.
In July 2015, CCC rated credit was already weakening ahead of a broader high-yield sell-off. At that time, the stresses were concentrated in cyclical sectors, particularly energy and commodities, and were increasingly associated with concerns about global growth5.
Back then, non-cyclical sectors – insurance, media, real estate, technology, telecommunications and utilities – represented only 31% of the CCC universe. Today, however, they account for 50% and much of the stress lies with telecoms and cable ('media') companies6. These businesses do not need a recession to come under pressure: elevated leverage and structurally weaker cash flows are enough to make refinancing increasingly challenging when combined with higher borrowing costs.
Sector composition of the stressed part of the high-yield markets, %
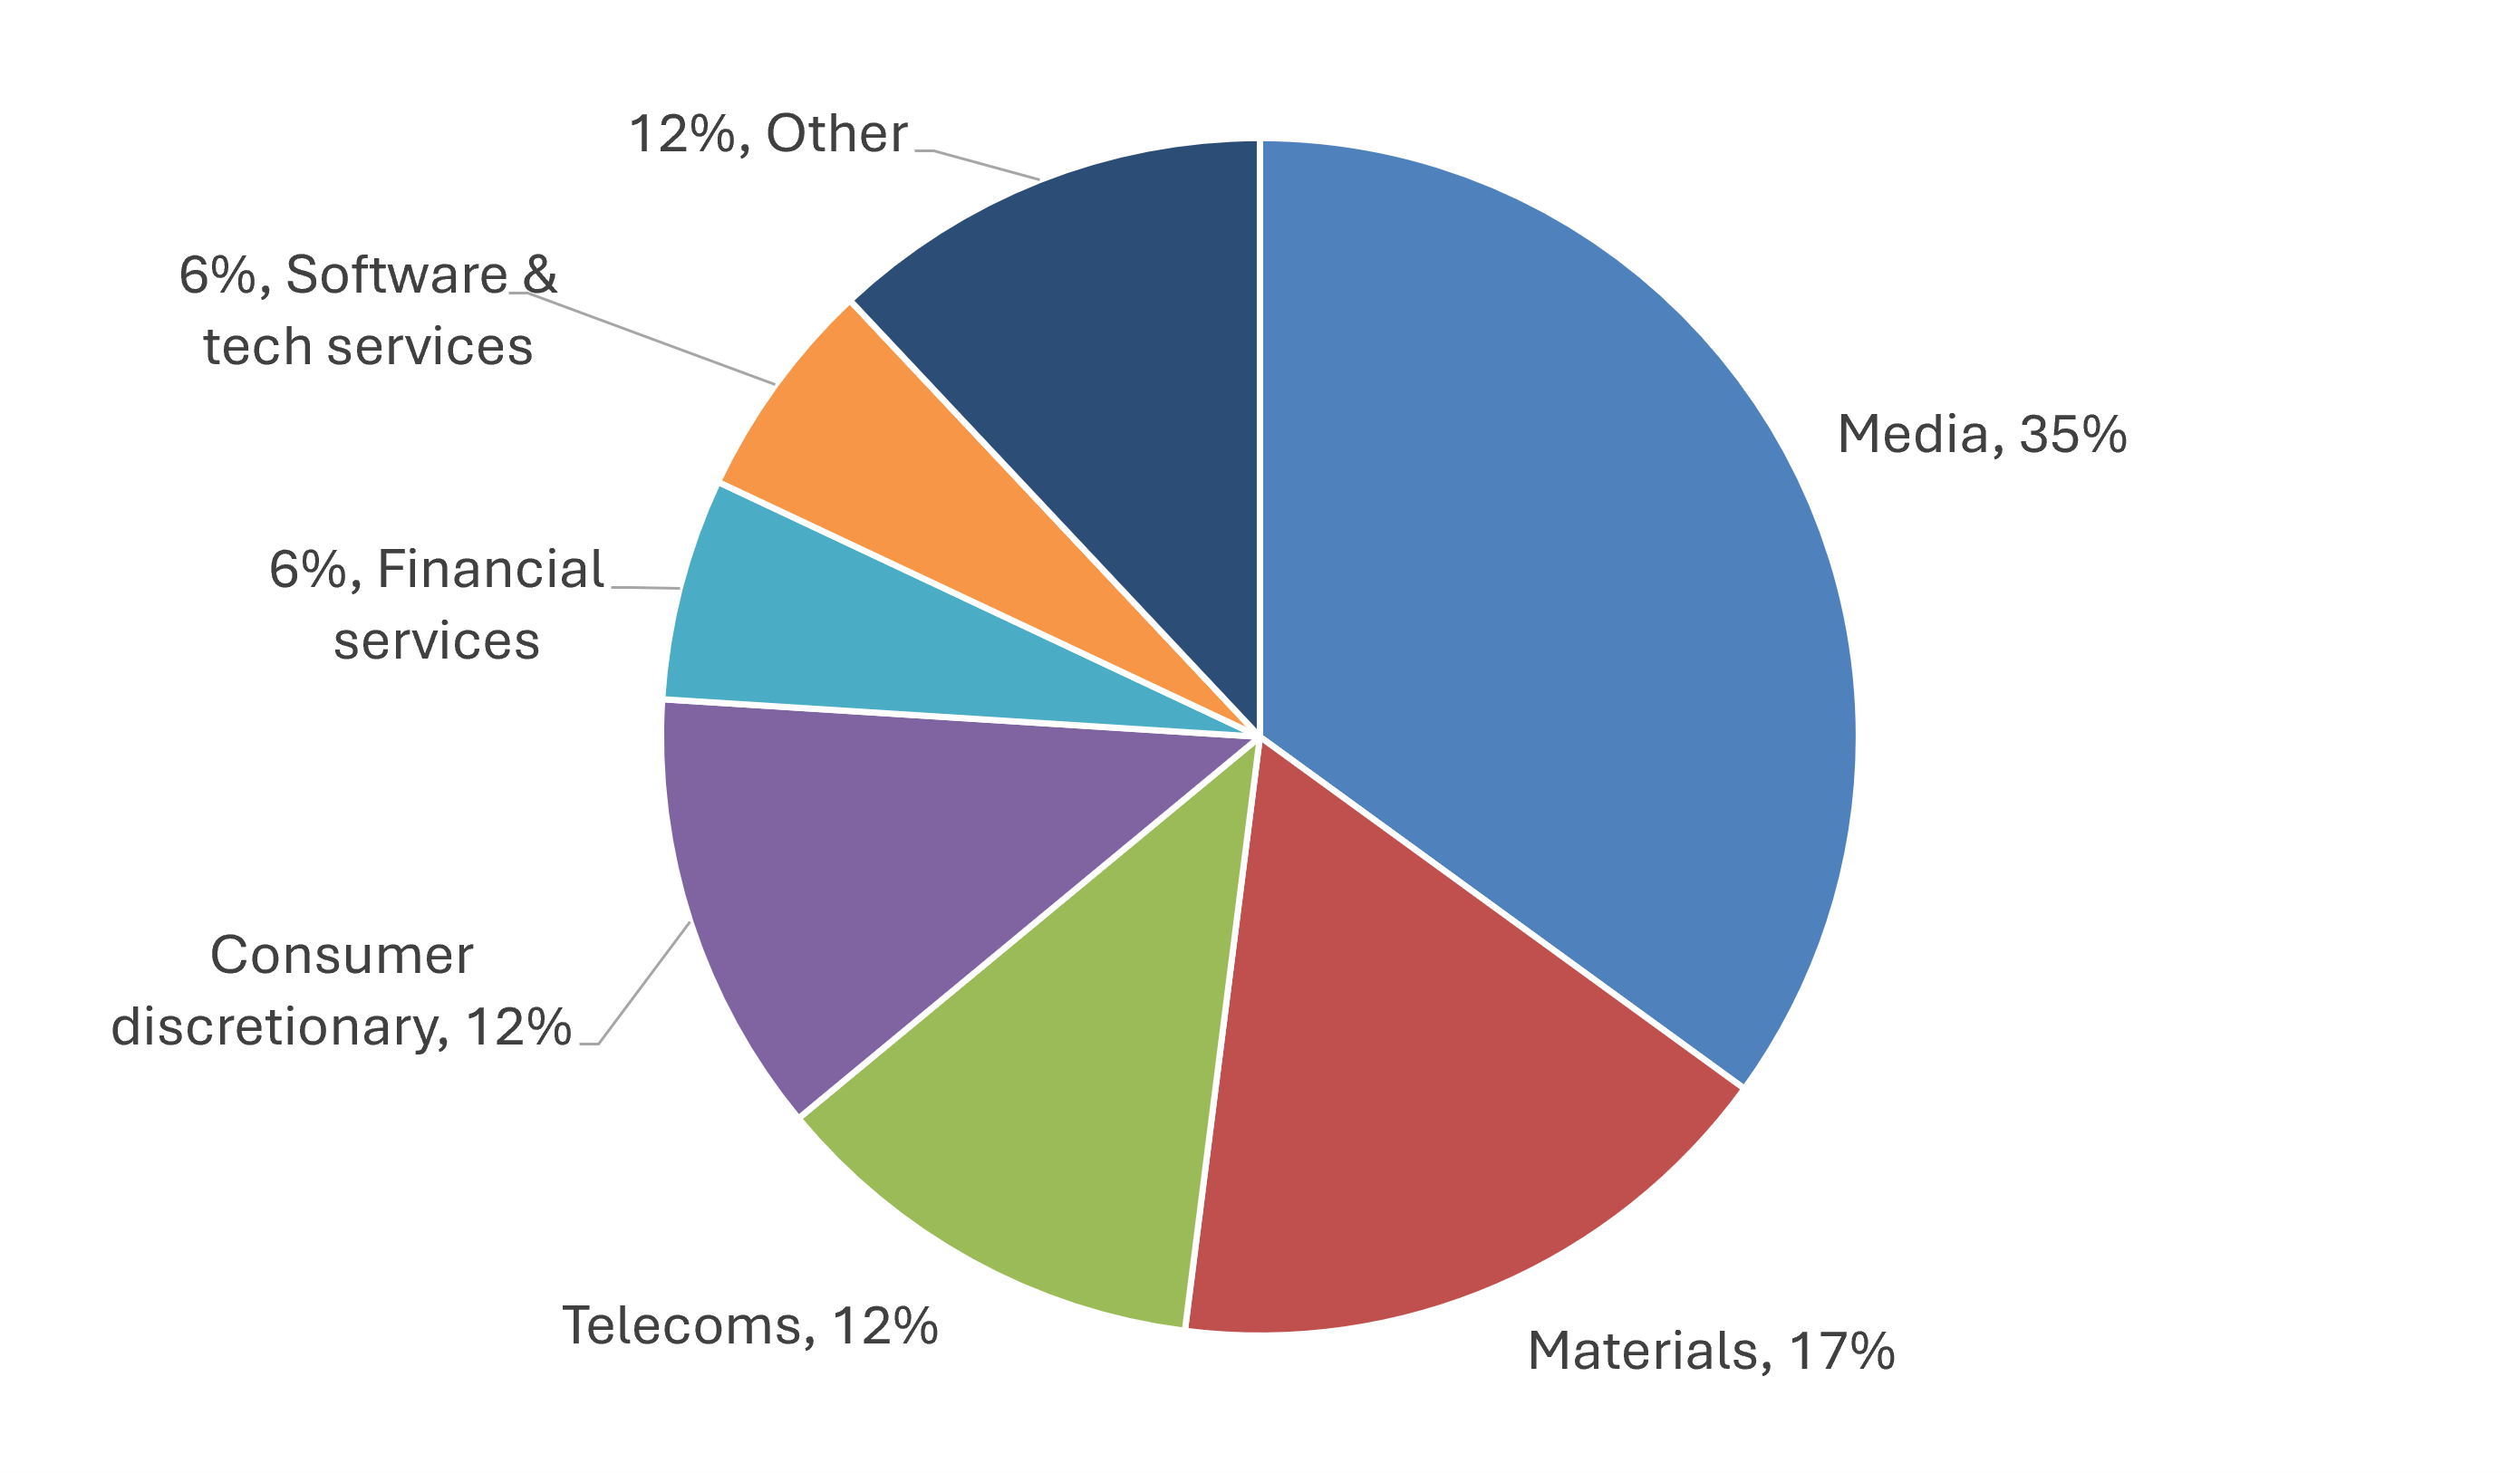
Moody's, Goldman Sachs Global Investment Research. "Stressed "credits are defined as those with spreads above 1,000bps. As at 8 October 2026.
At Artemis, we have generally avoided bonds issued by telecoms and cable companies, viewing them as structurally challenged. These businesses still need to address fundamental problems with their cash flows and capital structures.
Artemis continues to avoid most CCC bonds
So, while refinancing pressure is rising, it is increasingly concentrated in CCC-rated credit. High yield as an asset class is significantly higher quality than it was in previous cycles. And Artemis' high-yield funds are purposefully lighter in CCCs than the wider high-yield market.
Talk of 'bloodbaths' certainly makes for compelling headlines. And recent moves in certain areas of the high yield market deserve your attention; they reinforce the importance of active bond selection and can provide compelling opportunities. But don’t let scary headlines about one corner of the high-yield market ruin your breakfast.
Read more about recent happenings in high yield: No FOMO - Investors in high yield should not fear missing the AI boom and A tale of two credit markets
Notes and references
1. Bloomberg as at 3 November 2026
2. CE BofA Merrill Lynch Global High Yield Constrained Index, as at 30 September 2026
3. Board of Governors of the Federal Reserve System, 14 April 2016, Jerome H. Powell, Trends in Fixed-Income Markets
4. Board of Governors of the Federal Reserve System, 11 August 2026, Private Credit and Leveraged Loan Markets: Similarities, Differences, and Substitution
5. Bank for International Settlements, March 2016, BIS Quarterly Review: Uneasy calm gives way to turbulence
6. Goldman Sachs Global Investment Research, 9 October 2026, Global Credit Trader: 2027 Default Rates: Higher Risk Within the Left Tail
FOR PROFESSIONAL INVESTORS AND/OR QUALIFIED INVESTORS AND/OR FINANCIAL INTERMEDIARIES ONLY. NOT FOR USE WITH OR BY PRIVATE INVESTORS.
CAPITAL AT RISK. All financial investments involve taking risk and the value of your investment may go down as well as up. This means your investment is not guaranteed and you may not get back as much as you put in. Any income from the investment is also likely to vary and cannot be guaranteed.
This is a marketing communication. Before making any final investment decisions, and to understand the investment risks involved, refer to the fund prospectus (or in the case of investment trusts, Investor Disclosure Document and Articles of Association), available in English, and KIID/KID, available in English and in your local language depending on local country registration, available in the literature library.
Risks specific to Artemis Funds (Lux) – Global High Yield Opportunities
- Market volatility risk The value of the fund and any income from it can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
- Currency hedging risk The fund hedges with the aim of protecting against unwanted changes in foreign exchange rates. The fund is still subject to market risks, may not be completely protected from all currency fluctuations and may not be fully hedged at all times. The transaction costs of hedging may also negatively impact the fund’s returns.
- Bond liquidity risk The fund holds bonds which could prove difficult to sell. As a result, the fund may have to lower the selling price, sell other investments or forego more appealing investment opportunities.
- Higher-yielding bonds risk The fund may invest in higher-yielding bonds, which may increase the risk to capital. Investing in these types of assets (which are also known as sub-investment grade bonds) can produce a higher yield but also brings an increased risk of default, which would affect the capital value of the fund.
- Credit risk Investments in bonds are affected by interest rates, inflation and credit ratings. It is possible that bond issuers will not pay interest or return the capital. All of these events can reduce the value of bonds held by the fund.
- Derivatives risk The fund may invest in derivatives with the aim of profiting from falling (‘shorting’) as well as rising prices. Should the asset’s value vary in an unexpected way, the fund value could reduce.
- Leverage risk The fund may operate with a significant amount of leverage. Leverage occurs when the economic exposure created by the use of derivatives is greater than the amount invested. A leveraged portfolio may result in large fluctuations in its value and therefore entails a high degree of risk including the risk that losses may be substantial.
- Charges from capital risk Where charges are taken wholly or partly out of a fund's capital, distributable income may be increased at the expense of capital, which may constrain or erode capital growth.
- Emerging markets risk Compared to more established economies, investments in emerging markets may be subject to greater volatility due to differences in generally accepted accounting principles, less governed standards or from economic or political instability. Under certain market conditions assets may be difficult to sell.
- Income risk The payment of income and its level is not guaranteed.
- Counterparty risk Investments such as derivatives are made using financial contracts with third parties. Those third parties may fail to meet their obligations to the fund due to events beyond the fund's control. The fund's value could fall because of loss of monies owed by the counterparty and/or the cost of replacement financial contracts.
- ESG risk The fund may select, sell or exclude investments based on ESG criteria; this may lead to the fund underperforming the broader market or other funds that do not apply ESG criteria. If sold based on ESG criteria rather than solely on financial considerations, the price obtained might be lower than that which could have been obtained had the sale not been required.
Risks specific to Artemis Funds (Lux) – Short-Dated Global High Yield Bond
- Market volatility risk The value of the fund and any income from it can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
- Currency hedging risk The fund hedges with the aim of protecting against unwanted changes in foreign exchange rates. The fund is still subject to market risks, may not be completely protected from all currency fluctuations and may not be fully hedged at all times. The transaction costs of hedging may also negatively impact the fund’s returns.
- Bond liquidity risk The fund holds bonds which could prove difficult to sell. As a result, the fund may have to lower the selling price, sell other investments or forego more appealing investment opportunities.
- Higher-yielding bonds risk The fund may invest in higher-yielding bonds, which may increase the risk to capital. Investing in these types of assets (which are also known as sub-investment grade bonds) can produce a higher yield but also brings an increased risk of default, which would affect the capital value of the fund.
- Credit risk Investments in bonds are affected by interest rates, inflation and credit ratings. It is possible that bond issuers will not pay interest or return the capital. All of these events can reduce the value of bonds held by the fund.
- Derivatives risk The fund may invest in derivatives with the aim of profiting from falling (‘shorting’) as well as rising prices. Should the asset’s value vary in an unexpected way, the fund value could reduce.
- Charges from capital risk Where charges are taken wholly or partly out of a fund's capital, distributable income may be increased at the expense of capital, which may constrain or erode capital growth.
- Emerging markets risk Compared to more established economies, investments in emerging markets may be subject to greater volatility due to differences in generally accepted accounting principles, less governed standards or from economic or political instability. Under certain market conditions assets may be difficult to sell.
- Income risk The payment of income and its level is not guaranteed.
- ESG risk The fund may select, sell or exclude investments based on ESG criteria; this may lead to the fund underperforming the broader market or other funds that do not apply ESG criteria. If sold based on ESG criteria rather than solely on financial considerations, the price obtained might be lower than that which could have been obtained had the sale not been required.
Important information
The intention of Artemis’ ‘investment insights’ articles is to present objective news, information, data and guidance on finance topics drawn from a diverse collection of sources. Content is not intended to provide tax, legal, insurance or investment advice and should not be construed as an offer to sell, a solicitation of an offer to buy, or a recommendation for any security or investment by Artemis or any third-party. Potential investors should consider the need for independent financial advice. Any research or analysis has been procured by Artemis for its own use and may be acted on in that connection. The contents of articles are based on sources of information believed to be reliable; however, save to the extent required by applicable law or regulations, no guarantee, warranty or representation is given as to its accuracy or completeness. Any forward-looking statements are based on Artemis’ current opinions, expectations and projections. Articles are provided to you only incidentally, and any opinions expressed are subject to change without notice. The source for all data is Artemis, unless stated otherwise. The value of an investment, and any income from it, can fall as well as rise as a result of market and currency fluctuations and you may not get back the amount originally invested.